 Debt-Free
When you have several debts, “pay more” is not a plan. A useful debt payoff plan says what must be paid first, how much extra you can afford, which balance gets that extra money, and when to review the numbers. It also tells you what to do when a month goes wrong. You can build that plan without guessing your debt-free date or pretending your budget has more room than it does.
This guide is for people with US consumer debts such as credit cards, personal loans, car loans, and student loans. The terms of each account matter. Some loans have special benefits, prepayment rules, or tax considerations, so check your agreement before changing a payment strategy. If you cannot cover your minimum payments, start with the credit card hardship guide and contact the lender before using a payoff calculator.
Step 1: Put every debt in one list
For each account, record the current balance, annual percentage rate, required minimum payment, next due date, and whether the rate is fixed or promotional. Add a note for any past-due amount, late fee, or account in collections. Use current statements. A credit report can help you identify forgotten accounts, but the statement gives you the payment terms you need for a working plan.
This list is the foundation. Without it, you can easily double-count a balance, miss a promotional APR ending soon, or build a schedule around a minimum payment that already changed. Keep private account numbers out of a shared spreadsheet. A nickname such as “Card A” is enough for planning.
Sample debt inventory
Imagine Card A has a $4,000 balance at 25% APR with a $125 minimum. Card B has $2,000 at 18% APR with a $70 minimum. A personal loan has $6,000 at 9% with a $190 payment. The required payments add to $385. If you can put $500 toward debt each month, the extra payment is $115. This example is illustrative; actual interest and minimum formulas vary.
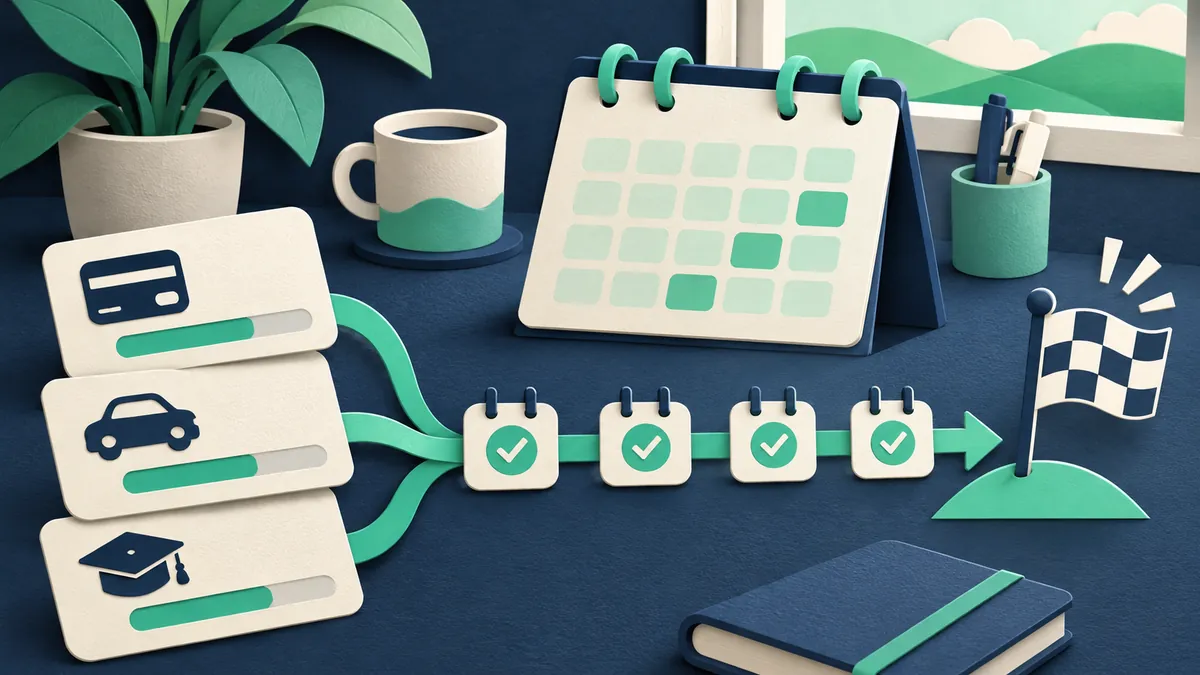
That $115 is the lever in your plan. It should go to one target debt while you keep the required payments on the others. Spreading an extra $20 or $30 across every account may feel fair, but it makes your progress harder to track and may delay your first paid-off balance.
Step 2: Find the payment amount you can repeat
Start with take-home income, then subtract essential costs, irregular expenses, and minimum payments. Include insurance, car repairs, prescriptions, and annual bills by setting aside a monthly amount. A debt plan that uses every spare dollar while ignoring predictable expenses will fail the first time a tire needs replacing.
If your income changes from month to month, set your base debt payment using a conservative month. You can add more in strong months. If $500 is only possible when you work overtime, do not make $500 the nonnegotiable base. Set a smaller amount you can keep paying and treat the rest as optional extra.
Keep a small buffer
You may choose to keep an emergency cushion before accelerating debt payments. The right amount depends on your circumstances and the cost of your debt. The point is practical: without any cash buffer, a small emergency often goes straight back on a credit card. You can work on a cushion and a debt plan at the same time.
If the budget shows no room for all required minimums, pause this payoff exercise. Call creditors, ask about hardship options, and consider a nonprofit credit counselor. A spreadsheet should reflect reality; it should not pressure you into an impossible payment.
Step 3: Choose one target debt
The two common methods are the debt avalanche and debt snowball. Avalanche targets the highest APR first, which generally minimizes interest when payments and terms are otherwise comparable. Snowball targets the smallest balance first, which can create a faster visible win. Either method requires you to pay the minimum on every other debt that remains current.
There is no universal correct method for every person. The right choice is one you can follow. Read the snowball versus avalanche guide for a fuller comparison and questions to help you choose. If you have a promotional 0% APR ending soon, a secured loan, or a past-due account, consider those terms before applying a simple ranking.
You can write the target at the top of your plan: “Pay all minimums and send the extra $115 to Card A on the same day each month.” That sentence is more useful than a vague promise to “focus on debt.” The plan should also state what happens if the extra $115 is unavailable: pay required minimums if you can, then restart the extra payment next month.
Step 4: Decide when the extra payment happens
Pick a date after income arrives and essential bills are accounted for. Some people schedule an automatic payment; others prefer a manual transfer after checking their balance. Either approach can work if you know when the payment posts and can avoid overdrafts. Confirm how your lender applies extra payments, especially on installment loans.
Making an extra payment earlier in a billing cycle can reduce interest on many revolving cards because interest is commonly calculated from daily balances. The exact effect depends on the account terms. The bigger win is consistency: one extra payment every month that you can afford.
When your target debt reaches zero, move the money that went to it toward the next target. That includes the extra amount and, if your budget permits, the old required payment. This is how the payment amount stays steady while individual balances disappear. Check the payoff figure and final statement before assuming an account is closed or fully settled.
Step 5: Estimate a debt-free date carefully
A payoff date is a forecast based on balances, APRs, payment amounts, and assumptions about future spending. It can change if rates move, you add new charges, a minimum payment changes, or your income shifts. Use it as a planning marker, not a promise. Review it after a statement cycle or major change, rather than checking it every day.
The Debt-Free Date System is a paid spreadsheet that shows estimated payoff dates and compares snowball and avalanche. You enter balances, rates, and payments in your own copy. It can show what a steady extra payment might do to the schedule. The minimum payments example explains why holding a fixed payment can change the timeline dramatically.
What to check in any calculator
Look at whether interest is modeled monthly or daily, whether payments are made at the start or end of the month, and how minimums change as balances fall. Ask whether new charges, fees, or promotional rates are included. If you are comparing two calculators, different assumptions may explain different dates. Your statements and loan agreements control what you actually owe.
Do not use a calculator result as an excuse to skip a payment. The next required payment and your cash flow matter more than a distant forecast. If the model says the plan is unaffordable, change the plan or seek help instead of changing the input to get a prettier date.
Step 6: Look for ways to reduce the cost
If a credit card APR is high, you can ask the issuer for a lower rate. There is no guarantee, but it is a direct question that may be worth asking. Our lower APR script gives you a preparation list and wording for the call. Confirm any new terms in writing and keep paying while the request is reviewed.
You can also look for recurring expenses that no longer serve you, sell items you do not need, or add income that fits your situation. Be realistic about time and health. A plan that requires seven days of extra work every week may be impossible to sustain. A smaller repeatable payment can be better than an ambitious number that collapses.
Watch for offers that promise to erase debt for a fee. The FTC's debt relief guidance warns about upfront charges and guaranteed outcomes. If you need structured help, look into nonprofit credit counseling and ask about all fees before signing up.
Step 7: Review once a month
On the same day each month, update your balances and check whether each payment posted. Compare the actual balance with your estimate. If there is a difference, look for interest, fees, new charges, or a changed APR. Adjust the next month's plan rather than feeling that you failed. Real life rarely follows a clean spreadsheet exactly.
Celebrate the useful milestones: a balance under a round number, a first account paid off, or a month without new credit card charges. These are signals that your system is working. They are also easier to control than a precise payoff date years away.
A plan you can copy today
“My required payments total ___. I can reliably add ___ each month. My target debt is ___ because I chose the ___ method. I will pay the extra on ___. If my income drops, I will pay what I can safely afford, contact the lender, and review the plan. I will update balances on the first weekend of every month.” Fill in the blanks using statements and your actual budget.
The first version does not have to be perfect. It needs to be honest, specific, and easy to repeat. Once the immediate bills are covered, the next best step is to put your debts on one page and choose the first target.